A legal due diligence checklist for a US acquisition earns its place only when it is tied to the deal thesis, the target's actual structure and verifiable records. A long generic request list can fill a data room and still miss the one lien, consent right, filing or lawsuit that changes price or closing.
US diligence runs on two layers. This checklist starts with federal regimes: merger control, foreign investment review, securities filings, patents, plant-closing notice and anti-bribery. It then covers state records such as entity status and secured-party filings, and flags where you must check the rules of a particular state. It is written for buy-side counsel and in-house teams.
What should be fixed before the first request list goes out?
Start with a short scope note. Name the target entities, the deal structure, the review period, the materiality rule, the states and countries in scope, the workstreams, exclusions and decision owners. Structure matters early. In a stock purchase or merger, the review focuses on the target entity as a whole. In an asset purchase, it follows the assets and liabilities the buyer agrees to take, and each transfer, consent and employee move needs separate work.
| Scope item | Decision it supports | Evidence owner | Completion test |
|---|---|---|---|
| Entity and authority | Can the seller and target sign and close? | Corporate counsel | Formation records, good standing and approvals reconciled |
| Capitalization | What exactly is being bought, and from whom? | Corporate counsel | Cap table traced to issuances, transfers and option grants |
| Liens and debt | What encumbers the shares or assets? | Finance counsel | UCC and other lien searches matched to debt documents |
| Material contracts | Which rights survive the deal, and on what terms? | Commercial counsel | Contract population reconciled; consent list built |
| Federal filings | Do HSR, CFIUS or sector rules apply? | Antitrust and regulatory counsel | Dated memo with sources and assumptions |
| Disputes and compliance | What exposure or restriction remains after closing? | Litigation and compliance counsel | Internal lists checked against court and agency records |
Agree an issue scale before review starts: critical, high, medium, informational and out of scope. Base the label on deal consequence, not on how surprising a document looks. Track every request and answer in one place; a due diligence question log works well for this.
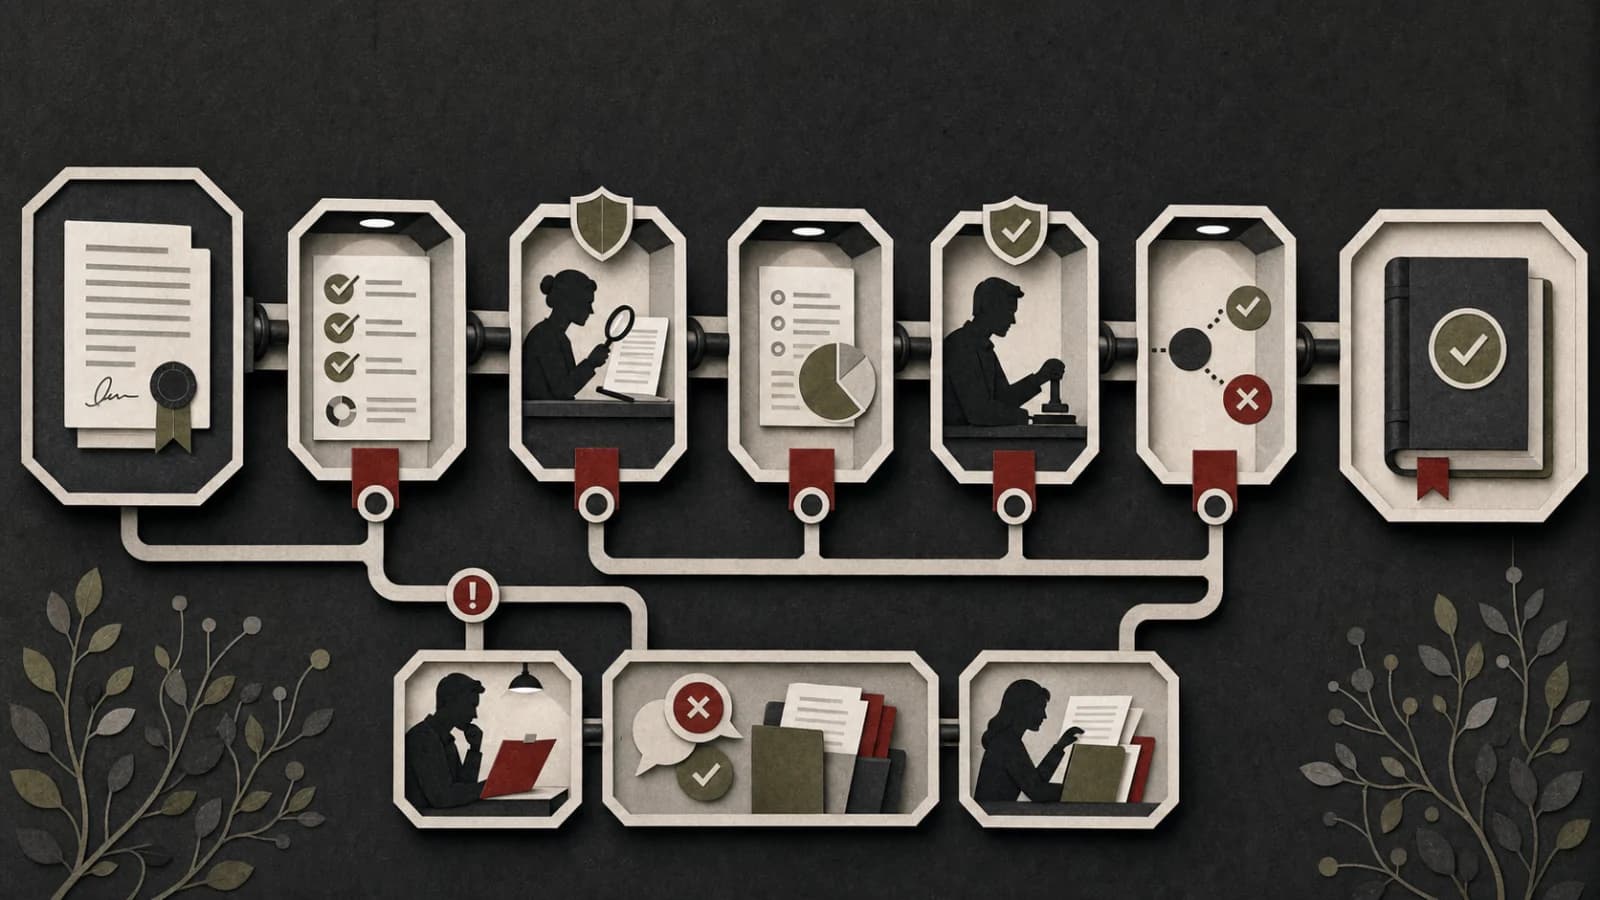
What does an end-to-end buy-side workflow look like?
| Phase | Operating question | Output |
|---|---|---|
| 1. Scope and request | What must be tested for this deal, entity set, period and materiality rule? | Approved scope note, request list and owners |
| 2. Data-room control | What was supplied, and which request does it answer? | Indexed data room with status for each request |
| 3. Public-record searches | What do state, federal and court records show? | Dated search results for entity, liens, litigation and IP |
| 4. Workstream review | What do corporate, contracts, employment, IP, regulatory and litigation reviewers find? | Findings linked to source documents |
| 5. Red-flag escalation | Which facts or gaps could change price, structure, timing or drafting? | Prioritized red-flag report |
| 6. Signing and closing | How will findings be handled in the purchase agreement and closing steps? | Response matrix tied to the current draft |
| 7. Post-closing handoff | Which obligations, consents and remediation items survive closing? | Action register with owners and due dates |
The phases loop. A late upload can reopen contract review, and a structure change can reopen the HSR or consent analysis. Record what triggered the change, which conclusion it affects and who signed off.
Which entity, lien and public-record searches should you run?
Corporate existence and authority are state-law questions. Get the certificate of incorporation or formation, bylaws or operating agreement, board and stockholder minutes, stock ledger, option plan records and any stockholders' or voting agreements. Then confirm status with the state. For a Delaware entity, the Division of Corporations offers an entity search, an entity status check and orders for a good standing certificate. For an entity formed elsewhere, use that state's filing office.
Search for liens next. Under UCC § 9-307(e), a registered organization organized under a state's law is located in that state. Under UCC § 9-501, most financing statements go to the filing office that the state designates. So a UCC search usually starts in the state of formation. Each state enacts its own text, and LII publishes the version most widely adopted by states, so check the enacted version in the relevant state.
If the target or seller is public, SEC EDGAR gives free public access to its filings. Compare periodic reports and material contracts on file with what the data room shows.
- Trace each stock issuance and transfer to board approval and consideration.
- Map options, warrants, convertibles, pledges and other rights to acquire equity.
- Find transfer restrictions, rights of first refusal, drag-along, tag-along and veto rights.
- Confirm good standing in the state of formation and each state where the target is qualified.
- Match every UCC filing to a debt document, payoff letter or release.
- Log missing minutes, unexplained cap table movements and stale filings as issues.
Which federal filings can affect signing and closing?
Two federal reviews often shape the timetable. Check them early, because they can change the signing-to-closing period and the conditions in the purchase agreement.
| Regime | What it does | What diligence should collect |
|---|---|---|
| Hart-Scott-Rodino Act | Requires premerger notification and a waiting period for certain acquisitions | Deal value, financials for size-of-person tests, overlaps, transaction documents |
| CFIUS | Reviews certain foreign investment in US businesses and certain real estate deals by foreign persons | Buyer ownership chain, foreign government interests, the target's technology and export classifications, sensitive data and real estate |
HSR. Under 15 U.S.C. § 18a, parties to a covered acquisition must file notification and observe a waiting period before closing. The waiting period ends on the 30th day after the FTC and the DOJ Antitrust Division receive the filings, or the 15th day for a cash tender offer, unless it is extended or ended early. The FTC lists the 2026 adjusted size-of-transaction threshold under section 7A(a)(2)(B)(i) as $133.9 million, and $535.5 million under section 7A(a)(2)(A), effective February 17, 2026. Size-of-person tests and exemptions also apply. Check the FTC's current thresholds page for every deal rather than relying on a saved checklist.
CFIUS. CFIUS is an interagency committee chaired by the Treasury Department. Its rules for covered transactions are in 31 CFR part 800, and its rules for real estate are in part 802. Under 31 CFR 800.401, a declaration is mandatory for two groups of deals involving a TID U.S. business. The first is where a foreign person in which a foreign government has a substantial interest acquires a substantial interest in that business. The second is certain deals where the business works with critical technologies that would need a U.S. export authorization for the foreign buyer. A mandatory filing is due no later than 30 days before the completion date. Diligence should therefore establish the buyer's ownership chain and the target's export classifications early.
How should material contracts be reviewed?
Build the contract population from finance, procurement, sales, real estate and IT records, not only from the data room. Group each master agreement with its amendments, orders, side letters, waivers and notices. Then extract the provisions the deal touches: term, renewal, termination, assignment, change of control, exclusivity, most-favored-customer terms, pricing, liability caps, indemnities, data and IP terms, and governing law.
| Review question | Required output | Escalate when |
|---|---|---|
| Will the relationship continue after closing? | Change-of-control or anti-assignment trigger, consent or notice path | An amendment or definition is missing |
| Can the counterparty exit? | Right, notice period, timing and cost | Termination terms conflict across documents |
| Are the economics reliable? | Pricing, adjustments and rebates | A side letter changes the schedule |
| Can the target use key assets? | License scope, ownership and restrictions | The chain of title is incomplete |
In an asset deal, anti-assignment clauses matter more, because each contract must move to the buyer. In a stock deal, change-of-control clauses matter more. Keep the clause text and section reference with every finding so later reviewers do not repeat the work. Who may approve a waiver or consent request is a separate question; a contract approval matrix helps the target record that.
What should the employment and IP workstreams check?
Employment. Collect headcount by site, offer letters, executive agreements, severance and change-in-control plans, restrictive covenants, contractor arrangements, benefit plans, and union or collective bargaining agreements. Check the WARN Act if the deal involves closures or layoffs. It applies to an employer with 100 or more employees, excluding part-time employees, or 100 or more employees who together work at least 4,000 hours a week, not counting overtime. An employer may not order a plant closing or mass layoff until 60 days after it serves written notice. On a sale of part or all of a business, 29 U.S.C. § 2101(b)(1) makes the seller responsible for notice up to and including the effective date of the sale, and the purchaser responsible after it. Ask counsel whether the states where the target operates add their own notice rules.
Intellectual property. Build an asset map that links each patent, trademark, copyright, domain name and key software asset to its creator, owner of record, assignments, licenses and the products that use it. Under 35 U.S.C. § 261, patents and applications are assignable by a written instrument. An unrecorded assignment is void against a later purchaser or mortgagee for value without notice, unless it is recorded at the USPTO within three months of its date or before the later purchase. Compare USPTO assignment records with the target's own records, and check that employee and contractor agreements assign inventions to the company.
For data, list the personal data the target holds, where it comes from, how it is shared, which processors it uses and what incidents it has had. Record which federal and state privacy laws counsel has assessed, and which questions remain open.
How should litigation, compliance and anti-bribery be tested?
Request pleadings, orders, settlement agreements, demand letters, agency correspondence, subpoenas, the internal litigation list, insurance notices and audit letters. Check them against federal and state court dockets where the target operates, and search under former names and subsidiaries. For each matter, record the court, parties, docket number, claims, stage, exposure, insurance position and source date. The litigation readiness plan guide explains how to hand pending matters to the owners who will run them after closing.
For anti-bribery, the DOJ describes the Foreign Corrupt Practices Act as prohibiting corrupt payments to foreign officials to obtain or retain business. It also requires companies whose securities are listed in the United States to keep accurate books and records and adequate internal accounting controls. Test what the target actually does. Sample third-party intermediaries, government touchpoints, gifts and hospitality, and past investigations, not just policy titles.
What makes a red-flag report decision-ready?
Separate fact, legal assessment, deal consequence and next step. Open with scope, dates, sources, assumptions and gaps. Link each issue to evidence and name an owner.
| Field | Practical entry |
|---|---|
| Verified fact | Short statement with document or public-record citation |
| Uncertainty | Missing fact, conflicting evidence or open legal question |
| Deal relevance | Price, structure, condition, covenant, indemnity, timing or integration |
| Proposed response | Request, specialist review, drafting change or closing deliverable |
| Owner and status | Named role, due date, open or closed |
Do not bury missing documents at the end. A gap can be the main finding. In the purchase agreement, a finding may become a specific indemnity, a closing condition, a covenant, a disclosure schedule item or a price change.
How does diligence carry into signing, closing and integration?
Link each condition, consent, filing, payoff letter, lien release and disclosure schedule to the issue and evidence behind it. After closing, hand ongoing obligations, contract notices, litigation dates, filings and remediation tasks to named owners.
Before signing, confirm that:
- scope changes and draft versions are reflected in the findings;
- high-priority findings had senior review;
- open requests show their consequence and owner;
- every report statement cites a document or public record;
- HSR, CFIUS and third-party consent status is documented;
- the purchase agreement addresses the agreed findings; and
- integration owners have accepted continuing tasks.
If the deal also involves a UK target or UK assets, see the UK version of this checklist. Gotham lets US legal teams research federal and state case law, the U.S. Code and federal regulations, review contracts at scale and draft in Word, in one workspace, with data for US customers stored in the United States. Every answer cites the passage it relies on.
Questions about US legal due diligence
What should a US legal due diligence checklist for M&A cover?
It should cover corporate records and good standing in the state of formation, UCC lien searches, SEC filings for public targets, material contracts, employment (including WARN Act exposure), intellectual property assignments, litigation, anti-bribery compliance, and federal filings such as HSR and CFIUS. Each request should tie to a question the deal team must answer, and findings should feed a red-flag report.
When does a deal need an HSR filing?
Under 15 U.S.C. § 18a, parties to certain acquisitions must file with the FTC and the DOJ Antitrust Division and wait before closing. The FTC lists the 2026 adjusted size-of-transaction threshold under section 7A(a)(2)(B)(i) as $133.9 million, effective February 17, 2026. Size-of-person tests and exemptions also apply, so counsel should check the FTC's current thresholds page for each deal.
Is a CFIUS filing ever mandatory?
Yes, in some cases. Under 31 CFR 800.401, a declaration is mandatory for certain transactions involving a TID U.S. business, including, subject to exceptions, where a foreign government has a substantial interest in the foreign acquirer or where the business deals in certain critical technologies. The filing is due no later than 30 days before the completion date.
Who gives WARN Act notice when a business is sold?
Under 29 U.S.C. § 2101(b)(1), the seller is responsible for notice of any plant closing or mass layoff up to and including the effective date of the sale. After that date, the purchaser is responsible. The WARN Act generally requires 60 days' written notice before a covered plant closing or mass layoff.